What to Do After a Motorcycle Accident in Seattle: A Rider's Step by Step
The minutes and days after a motorcycle crash decide far more than most riders realize. In a car, a bad move at the scene is often forgiven by a steel cage and airbags. On a bike you are exposed, the injuries run worse, and the same insurers that lowball every claim are already hunting for a reason to blame you. What you do in the first hour on I-5 or I-90, and in the weeks that follow, can make or break your Washington injury claim, and the reason comes down to how the crash is documented.
First: Get Safe and Get Checked
Before anything else, your health comes first. A motorcycle crash hides injuries behind adrenaline, and riders regularly wave off an ambulance only to wake up the next morning barely able to move. On a road as busy as I-405 or the approaches to the SR-520 floating bridge, a downed rider is also in danger from the next wave of traffic, and Seattle pavement is slick more often than not.
Move out of the lanes if you safely can, then call 911 so police and paramedics are on the way. Say yes to the medical evaluation. Adrenaline masks head injuries, internal bleeding, and spinal damage, and refusing care both risks your body and hands the insurer an argument that you were never really hurt.
Second: Understand Why the Documentation Matters So Much on a Bike
Here is the part that catches Seattle riders off guard. Washington is an at-fault state, not a no-fault state, and Personal Injury Protection is optional coverage you can add or reject. Many riders never buy PIP for the bike, which means their recovery leans almost entirely on two things: the at-fault driver's liability coverage and their own uninsured or underinsured motorist coverage. Both of those claims are won or lost on evidence. On top of that, Washington follows pure comparative negligence, so any recovery is reduced by your share of fault. That rule is more rider-friendly than the states that bar you outright, but it gives the insurer a powerful incentive to pin as much blame on you as it can, because every percentage point it shifts onto the rider is money off the check. The documentation you gather at the scene is not busywork. It is what keeps the insurer from writing the story for you.
Third: Document Everything You Can at the Scene
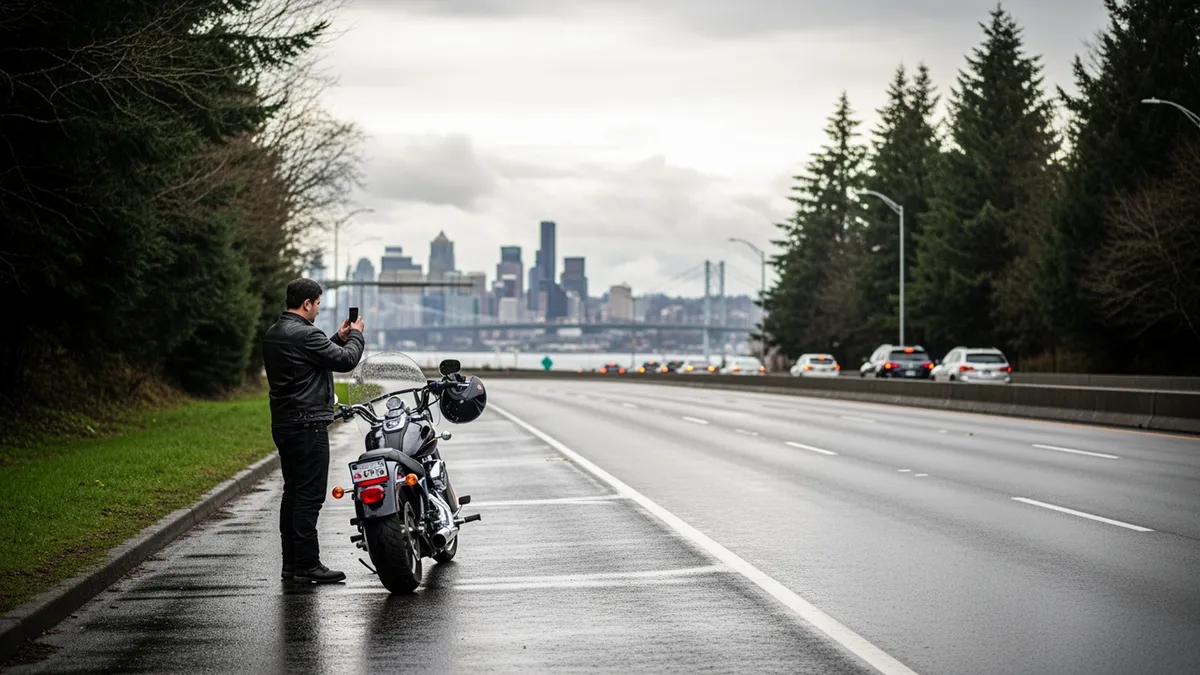
If you are physically able, the scene is a source of evidence that vanishes fast. Your phone is all you need. Downtown, remember you may be near the First Hill streetcar and rail tracks, which are a hazard in their own right, and grated metal bridge decks, painted lines, and wet leaves that made the road slick are worth capturing before the weather changes them.
- ✓ Photograph the whole scene. Both vehicles, your bike's position, the damage, the road, skid marks, signals, wet pavement, streetcar tracks, and the wider area. Wide shots and close-ups both matter.
- ✓ Get the other driver's information. Name, phone, insurance company, policy number, plate, and the make and model of the vehicle.
- ✓ Find witnesses now. A neutral person who saw the crash is gold. Get names and numbers before anyone leaves.
- ✓ Note the details. Time, weather, lane, direction, road conditions, and anything the other driver says. If they admit fault or apologize, remember it.
If your injuries make this impossible, that is exactly what a lawyer and an investigator are for. Never risk your health to get a photo.
Fourth: Watch What You Say
Here is where good, decent people accidentally sink their own case. In Washington, fault is not all-or-nothing, and it is not winner-take-all either. Under pure comparative negligence, your recovery is reduced by your share of fault, so if the insurer can convince a jury you were 30 percent responsible, it lops 30 percent off your recovery. On a rain-slick road, or crossing the grated deck of a bridge, the other insurer will be quick to suggest you simply lost control. That is exactly the blame it is trying to shift onto you.
So the words at the scene carry weight. A casual "I'm sorry" or "I didn't see him" can be twisted into an admission. Stick to the facts with the police, and do not guess about fault or apologize for a crash you did not cause. You do not have to accept blame to be polite.
Fifth: Get the Report and Preserve the Evidence
A Washington crash report is a foundational document for your claim, so make sure officers respond and give your account clearly. Meanwhile the clock is already running on the evidence itself. Traffic camera footage near the I-5 and I-90 interchanges, WSDOT cameras on the SR-520 and West Seattle bridges, and business security video along the SR-99 Aurora corridor are often overwritten within days. Skid marks fade, wet leaves get swept, and witnesses move and forget. Preserving that evidence quickly is one of the biggest reasons to get help early rather than waiting to see how you feel.
Sixth: Be Careful With the Insurance Company
Within a day or two an adjuster will likely call, sounding friendly and eager to help. Remember who signs that person's paycheck. Their job is to close your file for as little as possible, and they are especially aggressive with motorcycle claims because they know juries can be biased against riders and that comparative fault gives them room to chip the number down.
- ✓ You do not owe a recorded statement. The other driver's insurer will ask for one. It exists to catch you saying something they can use. You are not required to give it.
- ✓ Do not accept a fast, early offer. The first check almost always lands before you know the full extent of your injuries. Once you sign, the claim is usually over, even if you need surgery next month.
- ✓ Do not sign a blanket medical release. A broad authorization lets the insurer dig through your entire history hunting for a pre-existing condition to blame.
- ✓ Keep records of everything. Bills, treatment, missed work, and how the injuries affect daily life all build the real value of your claim.
Then: Know Your Deadline and Call Counsel
Washington generally gives an injured rider three years from the date of the crash to file a lawsuit, and a claim against a public body carries its own shorter notice requirements. That sounds like plenty of time, but it is not a reason to sit still. Evidence degrades, witnesses vanish, and insurers are happy to let months slip by while they "review" your file. Filing on time keeps your rights alive. Acting early keeps your case strong. Both point toward getting the facts reviewed while the evidence downtown and along the freeways is still fresh, especially when your bike likely carries no PIP and the fight is over how much fault the insurer can push onto you.
Have questions after a wreck? Janelle Bailey and the motorcycle accident lawyers in Seattle-Tacoma at Washington Injury Law (washingtoninjurylaw.com) review rider claims and explain your options.